
Actual cost is the amount really spent, as opposed to a budgeted, estimated or standard figure. In cost accounting it is the actual direct materials, direct labour and manufacturing overhead used to make a product. In project management, actual cost (AC, also called ACWP) is the cost recorded for the work performed so far.
Both meanings exist to be compared with something. Actual cost against a standard cost gives a variance that shows a plant manager where the money went. Actual cost against earned value tells a project manager whether the work is costing more than it is worth.
Evaluate your actual cost with our Actual Cost Calculator
Calculate your product’s actual cost with our Actual Production Cost Per Unit Calculator Online
Definition
About the video: it was made in March 2022 and still shows the old formula, Actual Cost = Direct + Indirect + Fixed + Variable + Sunken Costs, and describes a sunk cost as the cost of an error. Both are wrong, for the reasons explained under the formula below. The written definition and formula on this page are the corrected ones.
Definition: the actual cost of a manufactured product is the material actually used at the price actually paid, the labour actually worked at the rate actually paid, and the factory overhead actually incurred. Selling costs and administrative costs that do not help make the product are not part of it: they are expenses of the period, not product cost.
The accounting standards say the same thing more formally. IAS 2, which India applies as Ind AS 2 with the same paragraph numbers for these rules, defines the cost of inventories as “all costs of purchase, costs of conversion and other costs incurred in bringing the inventories to their present location and condition” (paragraph 10). Costs of conversion are direct labour plus “a systematic allocation of fixed and variable production overheads” (paragraph 12).
Paragraph 16 lists what stays out of inventory cost and goes straight to expense:
- abnormal amounts of wasted materials, labour or other production costs;
- storage costs, unless the production process needs them before a further production stage;
- administrative overheads that do not help bring the inventory to its present location and condition;
- selling costs.
India’s AS 2, notified under the Companies (Accounting Standards) Rules, 2021, words the last item as “selling and distribution costs”. Our guide to storage costs of inventory covers the storage rule in more detail.
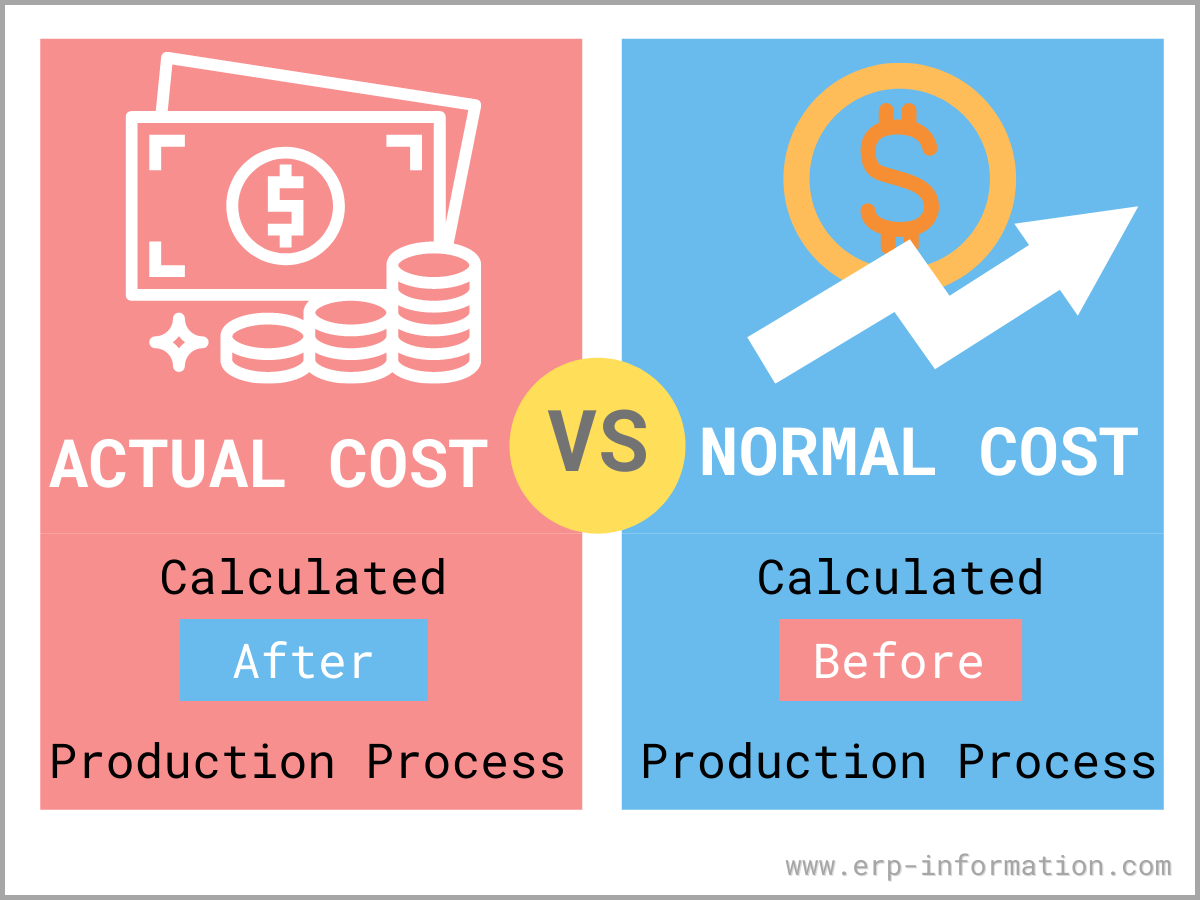
Cost accountants also use the word actual in a narrower sense, for a costing system. An actual costing system “only uses actual costs incurred and allocation bases experienced; it does not incorporate any budgeted amounts or standards”, so its overhead rate can only be worked out once the period’s overhead is known. A normal costing system uses actual materials and labour but a predetermined overhead rate, and a standard costing system uses predetermined figures for all three. The comparison below sets them side by side.
Actual cost formula
For one job, one batch or one period:
Actual Cost = Actual Direct Materials + Actual Direct Labour + Actual Manufacturing Overhead
Three components, because those are the three things a manufactured unit consumes. Everything else is a way of classifying those same three.
- Actual direct materials: the materials that can be traced to the product, in the quantity actually used and at the price actually paid.
- Actual direct labour: wages, payroll taxes and benefits of the people who work directly on the product, for the hours they actually worked.
- Actual manufacturing overhead: the production costs that are neither direct materials nor direct labour, such as indirect materials, indirect labour, factory utilities and depreciation, as actually incurred.
Why you cannot simply add every cost category together
A formula of the shape direct + indirect + fixed + variable still appears on several accounting websites, often with sunk costs added on the end. It counts the same money twice. Direct and indirect is one complete way of splitting total cost. Fixed and variable is a second complete way of splitting the same total. They are two questions about one pot of money, not four separate pots.
| Classification | The question it answers | Splits total cost into |
|---|---|---|
| Direct vs indirect | Can this cost be traced to one cost object? | Direct + Indirect = total |
| Fixed vs variable | Does this cost change when volume changes? | Fixed + Variable = total |
A machine operator paid by the hour is direct and variable. Factory rent is indirect and fixed. Count every cost once under each scheme, add all four totals, and you get exactly twice the real figure.
Sunk costs do not belong in the calculation at all. A sunk cost has already been incurred and will not change whatever you decide next, which is why it is irrelevant to a forward-looking decision. Waste is a different question: IAS 2 expenses abnormal amounts of wasted materials, labour or other production costs in the period instead of adding them to the cost of inventory.
If you make products, the actual cost per unit is:
Actual production cost per unit = (Actual material cost + Actual labour cost + Actual overhead cost) / Number of units produced
Where,
- Actual material cost = units of material used x price paid per unit
- Actual labour cost = labour hours used in production x wage paid per hour, including payroll taxes and benefits
- Actual overhead cost = the factory overhead actually incurred, such as factory electricity, rent and insurance. Office rent and electricity are period costs, not overhead.
One refinement applies when the number is used to value inventory in financial statements. IAS 2, Ind AS 2, India’s AS 2 and the US rule set by FASB Statement No. 151 all spread fixed production overhead over the factory’s normal capacity, not over a low actual output, and expense the part left over in the period. The worked example below shows the difference.
Calculation
Here is the formula applied to one month in a small factory. The figures are an illustration chosen to keep the arithmetic easy; the method is the standard one.
- Material used: 500 units at $5 each
- Direct labour: 200 hours at $10 an hour
- Factory overhead: electricity $500, rent $1,000, insurance $300
- Units produced: 1,000
Actual material cost = 500 x $5 = $2,500
Actual labour cost = 200 x $10 = $2,000
Actual overhead cost = $500 + $1,000 + $300 = $1,800
Actual production cost per unit = ($2,500 + $2,000 + $1,800) / 1,000 = $6,300 / 1,000 = $6.30
Same batch, three answers
The $6.30 is the pure actual cost. Two other legitimate numbers come out of the same month, depending on what the figure is for (our calculation, with the assumptions stated in each row):
| Method | Overhead charged to the 1,000 units | Cost per unit |
|---|---|---|
| Actual costing: every figure actual | $1,800 actually incurred | $6.30 |
| Normal costing: overhead at a rate set before the year, assumed $8.50 per labour hour | $8.50 x 200 actual hours = $1,700. The $100 gap is underapplied overhead, cleared at the period end | $6.20 |
| Inventory value under IAS 2 or Ind AS 2: rent and insurance treated as fixed, electricity as variable, normal capacity assumed at 1,300 units a month | Electricity $500 on actual use, plus fixed $1,300 x 1,000 / 1,300 = $1,000: $1,500 in all. The other $300 of fixed overhead is expensed in the month | $6.00 |
The normal costing row follows the textbook method: applied overhead is the predetermined rate multiplied by the actual activity, here labour hours. The IAS 2 row follows paragraph 13: fixed overhead is allocated on normal capacity, the amount per unit “is not increased as a consequence of low production or idle plant”, and variable overhead follows actual use. A quieter month would push the pure actual cost per unit up; the fixed overhead per unit in the inventory value would not rise.
What is normal costing?
Normal costing keeps actual direct materials and actual direct labour but charges overhead with a predetermined rate. In the words of the LibreTexts managerial accounting text, normal costing “tracks actual direct material costs and actual direct labor costs for each job and charges manufacturing overhead to jobs using a predetermined overhead rate”. The same text says most companies track product costs this way.
Normal cost = Actual direct materials + Actual direct labour + (Predetermined overhead rate x Actual activity)
Predetermined overhead rate = Estimated overhead for the year / Estimated activity for the year
The activity is usually direct labour hours, direct labour cost or machine hours. The rate is set before the year starts and is normally left unchanged during the year. In the Open Cost Accounting textbook’s example, $5,000,000 of budgeted overhead over 50,000 budgeted machine hours gives $100 per machine hour. A car that uses 200 machine hours is therefore charged $20,000 of overhead.
Why not wait for the actual overhead? Because, as OpenStax’s managerial accounting text explains, it is “available too late for management to make decisions”. Actual overhead figures usually arrive only at the end of the month, quarter or year. They also move around. Utility bills can rise in hot and cold months, and the same fixed cost spread over a different output gives a different unit cost: $1,300 of fixed overhead is $1.30 a unit at 1,000 units and $1.00 at 1,300 (our arithmetic).
At the year end, applied overhead rarely equals actual overhead. If less was applied than incurred, overhead is underapplied and the overhead account has a debit balance; if more was applied, it is overapplied, with a credit balance. Firms often close a small difference to cost of goods sold; when it is large, they spread it across work in process, finished goods and cost of goods sold.
Standard cost vs Actual cost
| Standard costing | Normal costing | Actual costing | |
|---|---|---|---|
| Direct materials | standard quantity at standard price | actual | actual |
| Direct labour | standard hours at standard rate | actual | actual |
| Overhead | standard rate | predetermined rate x actual activity | actual rate |
| Cost known | set at the start of the year | as each job is completed | after the period closes |
| Variances | materials, labour and overhead | overhead only | no over- or underapplied overhead, by construction |
A standard cost is an expected cost, usually set at the beginning of the fiscal year, for the prices a company expects to pay and the amounts it expects to use. The difference between standard and actual is a variance: favourable when the company spent or used less than the standard, unfavourable when it spent or used more. Our guide to purchase price variance covers the most common one.
Standard costing is allowed for financial statements, with a condition. IAS 2 and Ind AS 2 say the standard cost method “may be used for convenience if the results approximate cost”, with standards reviewed regularly; India’s AS 2 says the results must approximate “the actual cost”. So a company on standard costs still needs actual costs to prove its standards are close enough.
Actual cost example
Odoo’s manufacturing documentation has a clean example of actual cost against planned cost. The bill of materials for a putting green needs $50.00 of components and $15.00 of operations, so the planned cost of the manufacturing order is $65.00. The operations then ran ten minutes over, 40 minutes in total, and the order’s real cost came out at $70.00. Odoo then set the product’s cost to $67.50, the average of the earlier $65.00 and the new $70.00.
The $5.00 gap between $70.00 and $65.00 is an unfavourable cost variance (our calculation): the job cost more than planned. Had it cost less, the variance would have been favourable.
Cost variance is the difference between the planned or standard cost and the actual cost. It is worked out for each cost element, so a manager can see whether materials, labour or overhead caused it. For more on variances, read our article Purchase Price Variance (PPV).
What is actual cost in project management?
In earned value management (EVM), actual cost has a precise meaning. PMI’s Lexicon of Project Management Terms (version 5.0, January 2026) defines actual cost (AC) as “the realized cost incurred for the work performed on an activity during a specific time period”. US government guides call the same figure the actual cost of work performed (ACWP), and GAO’s cost guide notes that ACWP “is also known as Actual Cost (AC)”.
AC is not judged against the budget on its own. It is compared with earned value (EV, also called BCWP), the budget for the work actually completed. NASA’s guide for control account managers is blunt about it: earned value metrics “never compare just BCWS to ACWP”, because planned spending against actual spending says nothing about how much work was done. For how planned cost is built in the first place, see planned cost.
| Measure | Formula | How to read it |
|---|---|---|
| Cost variance (CV) | EV − AC | Negative: the work cost more than its budget |
| Cost performance index (CPI) | EV / AC | Below 1.0: the work cost more than planned |
| Estimate at completion (EAC) | AC + (BAC − EV) / CPI | Assumes past cost efficiency continues; GAO says it typically forecasts the lowest EAC |
| Percent spent | AC / BAC | Much higher than percent complete (EV / BAC) signals an overrun |
Worked example. NASA’s EVM tutorial uses a task with a $240k budget spread over 24 months. At the 12-month point, $100k of work was planned (PV), $60k of work was actually done (EV), and the accounting system showed $110k of actual cost (AC). That is a schedule variance of −$40k and a cost variance of −$50k. From the same figures (our calculation): CPI = 60 / 110 = 0.55, so each dollar spent bought about 55 cents of planned work, and the CPI-based EAC = 110 + (240 − 60) / (60 / 110) = 110 + 330 = $440k, close to double the budget. NASA’s reference card calls this estimate “typically a best case”.
Two traps when reading AC. First, a favourable cost variance can be an accounting artefact: GAO warns it can happen “when accounting accruals lag behind invoice payments”. Second, the US Department of Defense’s EVMS interpretation guide requires ACWP to be recorded “in the same period that earned value is measured”, using estimated actuals until the real costs reach the accounting system.
The rules behind these numbers changed in 2026. SAE published revision E of EIA-748, the earned value management standard, on 17 February 2026, cutting its guidelines from 32 to 27. The Department of Defense’s interpretation guide of 24 June 2026 now covers actual costs under Guideline 15, “Record Costs by EOC” (elements of cost). PMI’s PMBOK Guide is in its eighth edition, published in November 2025. Contractors that must meet these rules are covered in our guide to the DCAA-approved accounting system.
How do ERP systems calculate actual cost?
In an ERP system, actual cost is not a number someone types in. It comes out of the costing method chosen for each item and out of period-end runs that pull in late invoices and variances. This is what the current documentation of five systems says (editions checked on 15 October 2026).
| System and edition | Costing methods | How it reaches actual cost |
|---|---|---|
| SAP S/4HANA (2025 FPS02; Cloud Public Edition 2608) | Standard price or moving average price. The Material Ledger is mandatory; actual costing is optional and switched on plant by plant | During the period every goods movement is valued at standard and price differences are collected. At period end a costing run (app Edit Actual Costing Runs, CKMLCP) calculates a periodic unit price for each material and rolls variances up through the production levels. Revaluing inventory at that price is optional. |
| Oracle Fusion Cloud Cost Management (26D) | Standard, Actual, Perpetual Average and Periodic Average, set in cost profiles | The Actual method tracks the cost of each receipt and depletes receipt layers first in, first out. Work order completions are costed provisionally and their actual cost is calculated when the work order closes. |
| Microsoft Dynamics 365 Business Central | FIFO, LIFO, Average and Specific (actual cost bases) and Standard | The Adjust Cost - Item Entries batch job, or automatic cost adjustment, passes later costs, such as freight invoiced after the sale, to the entries they belong to. A production order’s actual cost is material, capacity or subcontracting, and manufacturing overhead. |
| Odoo 20.0 | Standard Price, FIFO and Average Cost (AVCO) | Each manufacturing order shows a planned MO cost and a real cost, built from components, the work center’s hourly cost times the operation’s duration, and each employee’s own hourly cost. |
| Microsoft Dynamics 365 Supply Chain Management | FIFO, LIFO, weighted average, moving average and standard cost | Under FIFO, issues carry a running average value until inventory close settles them by the item’s inventory model; Microsoft says most companies run inventory close as part of month-end close. |
Notice the pattern. SAP values the open period at standard and calculates the actual price only for the period just closed. Oracle costs completions provisionally until the work order closes. Business Central and Supply Chain Management adjust earlier entries after the fact. Every one of them confirms the textbook point: a true actual cost is a number you get after the event. That delay is the reason normal costing uses a predetermined overhead rate.
One more difference matters across borders. IAS 2 and Ind AS 2 allow only the FIFO and weighted average cost formulas (paragraph 25), and the IASB removed LIFO when it revised IAS 2 in 2003. That is why Odoo offers LIFO only as a picking order, “as LIFO is not allowed by IFRS”, and why Microsoft notes that LIFO is disallowed in many countries. Together with the bill of materials and its operations, the costing method decides what actual cost an ERP reports.
Benefits
Why companies track actual cost, and what it costs them to do so:
- Pricing. To set a sales price, a company needs to know what the item costs to make.
- Checking standards. Actual cost is the figure standards are measured against; the gap is the variance that shows where efficiency was gained or lost. SAP lets the periodic unit price from an actual costing run become the standard price for the next period.
- Financial statements. Inventory is measured at the lower of cost and net realisable value, and a company using standard costs must show that its standards approximate cost.
The limits are real too:
- It arrives late. Actual overhead is usually known only at the end of the month, quarter or year, too late for many decisions.
- It swings with volume. Fixed overhead spread over a smaller output raises the unit cost, which is why the accounting standards use normal capacity for inventory.
- It fluctuates. Overhead allocations based on short-term actual costs can spike or dip unexpectedly.
- It takes longer. Valuing ending inventory and cost of goods sold takes longer, because actual costs must first be compiled and allocated.
What does actual cost mean in tax and insurance?
India: actual cost under the Income-tax Act, 2025
India’s Income-tax Act, 2025 came into force on 1 April 2026 and repealed the Income-tax Act, 1961. For business assets, actual cost is now worked out under section 39, headed “Computation of actual cost”: the actual cost of a business asset is “the actual cost to the assessee, as reduced by the following amounts”. The amounts include any part of the cost met by another person or authority, GST for which input tax credit has been claimed and allowed, and any subsidy, grant or reimbursement relatable to buying the asset. Payments of more than ₹10,000 in a day to one person, made other than by a specified banking or online mode, are left out of actual cost.
Section 39 takes over from section 43(1) of the 1961 Act, under which “actual cost” meant “the actual cost of the assets to the assessee, reduced by that portion of the cost thereof, if any, as has been met directly or indirectly by any other person or authority”. The 1961 Act still applies to proceedings for tax years that began before 1 April 2026. The Income Tax Department’s Hindi text of section 43 renders actual cost as वास्तविक लागत (vastavik lagat).
Australia: the ATO’s actual cost method
The Australian Taxation Office offers two ways to claim working-from-home expenses: the fixed rate method and the actual cost method. Under the actual cost method you claim “the actual additional expenses you incur when working from home”, apportioned to the work-related share. You must keep receipts or bills and a record of the hours you worked from home. The fixed rate is 70 cents per work hour for 2024-25 and 2025-26; the ATO page we read on 15 October 2026 did not yet list a rate for 2026-27. For cars, the ATO’s equivalent is the logbook method, which claims “the work-related portion of your actual car expenses”; the alternative cents-per-kilometre rate for 2025-26 is 88 cents, up to 5,000 work-related kilometres.
United States: the IRS actual expense method
The IRS lets you work out a deductible car expense with either the standard mileage rate or the actual expense method. The actual expense method means working out “what it actually costs to operate the car” and claiming the business share of costs such as gas, oil, repairs, tires, insurance and depreciation. For 2026 there are two standard rates for business use: 72.5 cents a mile from 1 January and 76 cents a mile for costs on or after 1 July (IRS Announcement 2026-11). For a car you own, the standard rate has to be chosen in the first year the car is used in the business; in later years you can choose either method.
Insurance: actual cash value
People sometimes search for actual cost value, but the term insurance regulators use is actual cash value (ACV). Tennessee’s insurance regulator explains that ACV policies pay “replacement costs minus any applicable depreciation”, while replacement cost policies pay what the item would cost in today’s dollars. The Texas Department of Insurance adds that ACV policies cost less but also pay less when you have a claim.
Actual cost vs price, real cost and other terms
Several everyday words sit close to actual cost. This is how each one relates to it.
| Term | What it means | How it relates to actual cost |
|---|---|---|
| Price | “the amount of money for which something is sold” (Cambridge Dictionary) | Price is what the buyer pays; actual cost is what the seller spent. In business English, cost is the money spent to produce goods or services “before any profit is added”. |
| Budget, estimate, planned cost | What a company plans or expects to spend | The opposite of actuals, which Cambridge defines as money a company “really spends, rather than an amount of money that it plans or expects to spend”. |
| Standard cost | An expected cost set at the start of the year | Actual minus standard is the variance |
| Average cost (AVCO) | The weighted average cost of similar items, worked out for the period or at each receipt | Not the opposite of actual cost: it is one of the two cost formulas IAS 2 allows for ordinarily interchangeable items, to assign actual costs to the units sold and the units in stock |
| Real cost (economics) | A value adjusted for inflation; economists also use opportunity cost, the value of the next best alternative | Actual costs from different years are in different money: adjust both for inflation before comparing them |
| Sunk cost | Already incurred, cannot be avoided, not relevant to decisions | A past actual cost: record it, but leave it out of decisions about what to do next |
| Actual cash value | Insurance payout of replacement cost minus depreciation | An insurance term, not a cost accounting one |
FAQs
What is the actual cost formula?
Actual cost = actual direct materials + actual direct labour + actual manufacturing overhead. Divide by the units produced to get actual cost per unit. For inventory in financial statements, IAS 2 and Ind AS 2 base the fixed part of overhead per unit on normal capacity. A month of low output therefore does not raise the unit cost, and the unallocated overhead is expensed in that period.
What is actual cost in project management?
In earned value management, actual cost (AC), also called actual cost of work performed (ACWP), is the cost actually incurred and recorded for the work performed in a period. It is compared with earned value: cost variance = EV minus AC, and cost performance index = EV / AC. A CPI below 1.0 means the work cost more than planned.
What is the normal costing formula?
Normal cost = actual direct materials + actual direct labour + (predetermined overhead rate x actual activity). The predetermined overhead rate is estimated overhead for the year divided by estimated activity, such as direct labour hours or machine hours, and it is set before the year begins.
What is the difference between actual costing and normal costing?
Both use actual direct materials and actual direct labour. Actual costing charges overhead at the actual rate, which is known only after the period closes. Normal costing charges overhead at a rate set in advance multiplied by actual activity, so a job can be costed as soon as it is finished. At the period end, the gap between applied and actual overhead is cleared as underapplied or overapplied overhead.
What is the total fixed cost?
Total fixed cost is the sum of the costs that stay relatively constant whatever the volume of production, such as depreciation and maintenance of factory buildings and equipment and the cost of factory management. Fixed is not the same as direct: fixed versus variable asks whether a cost moves with volume, while direct versus indirect asks whether it can be traced to one product. Fixed costs are fixed in total, not per unit: $1,300 of fixed overhead is $1.30 a unit at 1,000 units and $1.00 at 1,300 units.
What is actual cost under the Income-tax Act?
Section 39 of India’s Income-tax Act, 2025, in force from 1 April 2026, sets out how to compute the actual cost of a business asset. It is the cost to the assessee, reduced by any part met by another person or authority, by GST for which input tax credit has been claimed and allowed, and by any subsidy, grant or reimbursement for buying it. Section 39 replaced section 43(1) of the Income-tax Act, 1961.
Which actual cost figure do you need?
The right actual cost figure depends on the decision in front of you:
- Pricing a job or checking a quote: the job’s actual materials and labour, with overhead at your predetermined rate if you need the number before the month closes (normal costing).
- Valuing inventory under IFRS, Ind AS or AS 2: actual purchase and conversion costs, with fixed overhead per unit based on normal capacity; abnormal waste, selling costs and non-production administrative costs go to expense.
- Running standard costs or an ERP on standard prices: compare actual cost with standard to get the variances, and check that the standards still approximate actual cost.
- Managing a project: track AC against earned value, not against the plan alone. CV and CPI tell you whether the work is costing more than it is worth.
- Business assets under India’s income tax: the asset’s actual cost under section 39 of the Income-tax Act, 2025, net of subsidies and GST input credit claimed.
- Car or home-office claims in Australia or the US: the actual cost or actual expense method needs receipts and a usage record; the fixed rates need less paperwork.
To run the numbers, use our actual cost calculator or the actual production cost per unit calculator.
How we researched this page (15 October 2026): we read the current text of IAS 2 (EU consolidated version of 8 March 2026), Ind AS 2 and AS 2 (India) and FAS 151 (US); the OpenStax, LibreTexts and Open Cost Accounting textbooks; GAO’s Cost Estimating and Assessment Guide, the US Department of Defense EVMS Interpretation Guide (June 2026), SAE EIA-748-E and PMI’s Lexicon (version 5.0); the current documentation of SAP S/4HANA, Oracle Fusion Cloud, Microsoft Dynamics 365 and Odoo 20; India’s Income-tax Act, 2025; and ATO, IRS and US state insurance regulator guidance. Figures marked as our calculation or illustration are ours; every other figure comes from the cited source. An earlier version of this page and its diagram added fixed, variable and sunk costs on top of direct and indirect costs, which counts the same money twice. We corrected the text in August 2026 and the diagram in October 2026.
References
- IAS 2 Inventories, paragraphs 10 to 27, in Commission Regulation (EU) 2023/1803, consolidated version of 8 March 2026 (EUR-Lex)
- IFRS Foundation: IAS 2 Inventories, standard page and amendment history
- ICAI: Ind AS 2 Inventories (2025-2026 edition)
- Ministry of Corporate Affairs: AS 2 Valuation of Inventories (Companies (Accounting Standards) Rules, 2021)
- FASB: Statement No. 151, Inventory Costs (November 2004)
- HKICPA: HKAS 2, reproducing the IASB Basis for Conclusions on IAS 2 (LIFO)
- OpenStax: Principles of Accounting, Volume 2, 6.1 Calculate predetermined overhead rates
- OpenStax: Principles of Accounting, Volume 2, 4.4 Compute a predetermined overhead rate
- OpenStax: Principles of Accounting, Volume 2, 4.6 Determine and dispose of underapplied or overapplied overhead
- OpenStax: Principles of Accounting, Volume 2, 4.2 The three major components of product costs
- OpenStax: Principles of Accounting, Volume 2, 8.1 How and why a standard cost is developed
- OpenStax: Principles of Accounting, Volume 2, 10.1 Relevant information and sunk costs
- LibreTexts: Managerial Accounting, 2.4 Assigning manufacturing overhead costs to jobs
- Open Cost Accounting (Brian D. Knox, Boise State University), Chapter 4: normal costing
- Open Cost Accounting, Chapter 7: standard costing
- AccountingTools: What is actual costing?
- OpenStax: Principles of Economics 3e, 19.2 Adjusting nominal values to real values
- OpenStax: Principles of Economics 3e, 2.1 Opportunity cost
- Cambridge Dictionary: price
- Cambridge Dictionary: cost
- Cambridge Dictionary: actual, actuals
- GAO: Cost Estimating and Assessment Guide, GAO-20-195G (March 2020)
- US Department of Defense: Earned Value Management System Interpretation Guide (24 June 2026)
- US Department of Defense: Integrated Program Management glossary
- SAE: EIA748E Earned Value Management Systems (2026-02-17)
- PMI: Lexicon of Project Management Terms, version 5.0 (January 2026)
- PMI: PMBOK Guide, Eighth Edition
- NASA: Earned value management tutorial
- NASA: Integrated Program Management reference card (June 2026)
- NASA: Reference guide for project control account managers
- SAP Help: Actual Costing, SAP S/4HANA 2025
- SAP Help: Edit Actual Costing Runs (CKMLCP)
- SAP Help: Actual Costing, SAP S/4HANA Cloud Public Edition
- Oracle Fusion Cloud SCM 26D: Supported cost methods
- Oracle Fusion Cloud SCM 26D: Cost accounting for manufacturing
- Microsoft Learn: Business Central design details, costing methods
- Microsoft Learn: Business Central design details, cost adjustment
- Microsoft Learn: Business Central design details, production order posting
- Microsoft Learn: Dynamics 365 Supply Chain Management, inventory close
- Odoo 20.0 documentation: Inventory valuation
- Odoo 20.0 documentation: Manufacturing order costs
- CBDT press release: Income-tax Act, 2025 comes into force from 1 April 2026
- Gazette of India: The Income-tax Act, 2025 (Act No. 30 of 2025)
- Income Tax Department: section 39, Income-tax Act, 2025
- Income Tax Department: section 43, Income-tax Act, 1961
- Income Tax Department: section 43 (Hindi text)
- Australian Taxation Office: Actual cost method for working from home expenses
- Australian Taxation Office: Logbook method for car expenses
- IRS: Topic 510, Business use of car
- IRS: Internal Revenue Bulletin 2026-29, Announcement 2026-11
- Tennessee Department of Commerce and Insurance: Actual cash value vs replacement cost
- Texas Department of Insurance: Replacement cost or actual cash value
Using Google Search? Add erp-information.com as a preferred source.